Your new post is loading...
The federal government wants the option to take equity in publicly traded companies that tap into its new loan program for big business, The Logic has learned. On Monday, Finance Minister Bill Morneau announced the Large Employer Emergency Financing Facility (LEEFF), through which Ottawa will give credit of $60 million or more to firms with at least $300 million in annual revenue that “make meaningful investments in Canada, and provide jobs to Canadians.” The program is designed to let the federal government act as a lender of last resort to large companies that would be viable if not for the economic impact of the COVID-19 pandemic. To secure a loan through LEEFF, companies must show they intend to “preserve employment,” and agree to restrictions on executive pay, dividends and share buybacks.
It may be a painful fact to contemplate during these locked-down days, but last year the world was more mobile than ever, with people taking 4.6bn flights. In April this year, though, planes carried just 47m passengers; that level of mobility, annualised, would set the clocks back to 1978. The virtual halt to travel has exacerbated the global economy’s woes, complicating trade ties, upending business and devastating the tourism industry. Little wonder that governments want to restore links. An idea gaining favour is the creation of travel “bubbles”, binding together countries that have fared well against the coronavirus. A closer look yields some grounds for optimism. The Economist has identified potential bubbles that account for around 35% of global gdp, 39% of all trade in goods and services and 42% of the world’s spending on tourism. But the challenge of connecting them also underscores how hard restarting the global economy will be.
Companies have always strived to present their financial results in the most flattering light. Now some are going a step further, presenting a new customised metric they are calling ebitdac: earnings before interest, tax, depreciation, amortisation – and coronavirus. This week Schenck Process, a German manufacturing group, added back €5.4 million of first-quarter profits that it said it would have made were it not for the hit caused by state-mandated lockdowns. Its operating profit for the period - “adjusted ebitdac” of €18.3 million – was almost 20 per cent higher than the same period a year earlier, rather than 16 per cent lower. Schenck Process is not the only company tinkering with the presentation of its results. When The Azek Company, a Chicago-based manufacturer of building products, raised $325 million (€301 million) of junk bonds last week it included a term that would allow it to add back “lost earnings” as a result of Covid-19 in future. That was a first for the corporate debt market, according to research firm Covenant Review.
Lloyd’s of London is likely to pay out $3.0 billion-4.3 billion in insurance claims related to the coronavirus pandemic, similar to losses from the 9/11 attacks, it said on Thursday. The pandemic has locked down economies around the world, bringing businesses, events and travel to a halt and leading to hefty claims. Global non-life underwriting and investment losses may hit a record $203 billion in 2020, the commercial insurance market added. Zurich Insurance said on Thursday it expected $750 million in non-life pandemic claims this year. In a double blow, insurers have also lost money due to falling markets, slashing the investments they use to pay out claims. “I don’t think anyone in our industry has ever seen both happen at once,” Lloyd’s Chief Executive John Neal told Reuters.
Call it Justin bucks, Tru-dough, but $2,000 in the bank is $2,000 in the bank. Every four weeks, if you’re a CERB applicant — that’s Canada Emergency Response Benefit — you’ll get the cash to help float you through the next month of life. It’s like regular income; you’ll be taxed on it down the line. Otherwise, it’s sweet cash money, even if it’s not really all that much. At $500 per week, it’s less than a person working 40 hours per week earning $15 an hour would take home. Better than nothing. Obviously, that depends on where you live. Don’t even bother trying to live on CERB in Vancouver, where rent for a one-bedroom apartment is $2,006 on average per month, or Toronto, where a one-bedroom apartment averages $2,213 per month, although you might be able to scrape by in the ‘burbs, such as Brampton, Ont., or Burnaby, B.C.
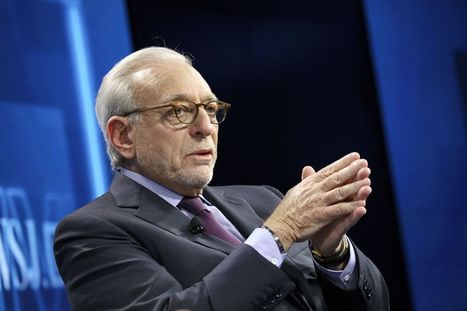
A high-stakes hedge fund strategy of betting on a small number of stocks returned bumper profits in April after landing firms with agonizing losses just a month earlier. So-called activist hedge funds, which build stakes in companies and demand changes in a bid to boost share prices, posted their best month since late 2012, according to Hedge Fund Research data. That’s after suffering their worst-ever losses amid the virus-fueled sell off in March. Billionaire Nelson Peltz’s Trian Partners gained more than 12% in April after losing 16% the previous month, according to an investor letter. Hedge fund CIAM, which makes bets on European companies, rose 14% for its best-ever month after shedding 27.5% in March, while Accendo Capital surged 26.3% to record its best monthly gains in April, separate letters showed.
EasyJet founder Sir Stelios Haji-Ioannou is offering £5m to any “whistleblower” providing him with information that scuppers the budget airline’s 107-plane order from Airbus. Haji-Ioannou, who has been attempting to force easyJet’s board to cancel the order for months, says the £4.5bn deal will leave the carrier without enough cash to survive the coronavirus crisis. In an open letter, the entrepreneur, who owns a third of the airline, said: “EasyJet is currently run by certain directors that I can only regard as ‘scoundrels’. That remains my honest opinion. [...] He has called a shareholder meeting to remove four of easyJet’s directors – chairman John Barton, chief executive Johan Lundgren, finance director Andrew Findlay, and independent non-executive director Andreas Bierwirth – if the airline does not cancel the orders.
Rich and poor countries alike are facing an unprecedented economic crisis as they attempt to contain the impact of the COVID-19 pandemic. A downturn of this magnitude can cause tremendous long-term damage, with critical economic linkages between employees, businesses, and banks at risk of disappearing forever. Scores of firms will close permanently unless urgent action is taken. The threat is even more significant for emerging economies, where the economic costs of social distancing are likely to be higher, and where vulnerable small and medium sized enterprises with low cash reserves account for a much larger share of the economy than in rich countries, which moreover can rely on extensive social and economic safety nets.
UK politicians have urged the chancellor to exclude businesses using tax havens from state aid, with a moratorium on dividends and curbs on CEO pay. The return to work may be dominating discussion in the UK at the moment but some politicians are attempting to use corporate governance as criteria for managing aid to large companies. The MPs, mostly Labour but some Liberal Democrats and Scottish Nationalists, have called on the chancellor, Rishi Sunak, to exclude businesses using tax havens from state aid. They also want to see a moratorium on dividends and buybacks and curbs on excessive executive pay.
The COVID-19 pandemic is causing financial distress to economically viable firms on an unprecedented scale. In this post, we introduce the novel idea of creditor cooperation duties to stabilize corporate workouts. The prospect of widespread defaults by viable firms triggered by the COVID-19 pandemic has prompted emergency legislation around the globe. To a significant degree, these measures aim to keep distressed firms out of formal bankruptcy proceedings. For example, duties to initiate such proceedings have been suspended in Germany, Italy, and Spain; rules that govern the liability of directors of near-insolvent or insolvent companies have been relaxed in Australia, Singapore, Germany, and the UK.
Twitter will allow employees to work from home for as long as they want. Twitter CEO Jack Dorsey told his employees Tuesday that many of them will be allowed to work from home in perpetuity, even after the coronavirus pandemic ends, according to a company spokesperson. “Opening offices will be our decision,” the spokesperson said. “When and if our employees come back, will be theirs.” [...] Major tech companies such as Facebook, Google and Microsoft were early to move to a work-from-home model and have also been the most cautious in planning for moving employees back into the office. Google has told employees that the vast majority of them will work from home until 2021, though some will return in the early summer. Facebook will similarly start to reopen offices after the July 4 weekend but will let employees who are able to work from home do so until next year.
In “La La Land,” Damien Chazelle’s Oscar winning film, the audience thinks it has a formulaic Hollywood love story on its hands: boy and girl meet; boy and girl fall in love; boy and girl break up; and boy and girl get back together. But in a twist on the classic love story, boy and girl never get back together, and although they still might love each other on some level, it’s clear they will never find their way back to each other because of, well, life. This year we have seen how easy it is for life to intervene and change everything – just as COVID-19 had been declared a global pandemic and the inevitability of its negative economic effects started to become clear, we outlined a number of key areas where we expected the M&A market to be impacted and discussed proactive steps boards should take in light of market disruption to preserve long-term value. In the seven (long) weeks since, we have observed (from our respective home offices) M&A love stories fall apart as a result of the pandemic in a number of different ways, including:
Once seen as a job with few critical responsibilities beyond the “care and feeding” of the company’s directors and serving as a scribe at board meetings, the corporate secretary has evolved into a key focal point within a public company and the internal gear-hub of corporate governance. [...] There is a sign on the door at each end of every New York City subway car that alerts passengers, “Riding or moving between cars is prohibited.” The reason for curbing what was once a common practice of city straphangers[1] is… it’s hazardous![2] This may sound crazy, but being a corporate secretary at a corporation can at times feel like riding between cars. How so?
|
HOUSTON, May 13 (Reuters) - Shareholder activists prodding Exxon Mobil Corp on climate-change proposals are backing calls for an independent board chairman as the oil major steps up efforts to keep climate proposals off its ballot. [...] “The company has been a laggard on financial performance, climate risk management and lobbying disclosure for quite some time now,” said Thomas DiNapoli, New York state comptroller and head of the state’s biggest pension fund. “Its peers in Europe, many of whom have independent board chairs, are outperforming Exxon on all these,” he said. [...] Proxy adviser Glass, Lewis & Co separately called for splitting the two roles. On Tuesday, Institutional Shareholder Services urged holders to vote “against” creating an independent chairman, reversing its stance from a year ago. Exxon’s naming of a lead director able to meet with shareholders changed its view, ISS wrote.
When global equity markets lost around US$16 trillion of their value in a single month this year, the wealthy found themselves no more protected from financial loss than anyone else. According to the Bloomberg Billionaires Index, the world’s 500 richest people collectively saw nearly US$950 billion evaporate in the first 10 weeks of 2020, a 16 per cent fall. Most of it went in the four weeks from mid-February to mid-March, including US$330 billion on a single day, Thursday March 12. Those with the luxury of a long-term perspective can hope for an eventual share price recovery. Even if this is years away, history suggests it will come. But those with more urgent financial needs must accept a painful reality: investors stand to lose up to US$490 billion of dividend payments in the full calendar year, based on the preliminary worst-case forecast for the Janus Henderson Global Dividend Index.
What makes a central bank “independent?” As most central bank scholars and policy-makers would likely answer that question, “it depends” – it depends on the bank, the function it is performing, and the political-economy of the times. Still, as complicated as the concept of central bank independence is, many experts could likely agree on at least one indicium of independence: a central bank’s legal freedom to make certain decisions free from executive branch interference – at least where certain of its core functions, like monetary policy, are concerned. In a recent article, we compare the way that two different legal frameworks – in the U.S. and the UK – legally empower their executive branches to direct or override decisions normally reserved to their independent central banks.
Norway’s $1-trillion wealth fund is excluding some of the world’s biggest commodities firms from its portfolio, including Glencore and Anglo American, because of their use and production of coal. Underlining the growing role of climate considerations for long-term investors, the fund is also excluding German utility RWE, South African petrochemicals firm Sasol and Dutch company AGL Energy over their use of coal. Norway’s parliament agreed in June 2019 to toughen existing limits on coal investments by the world’s largest fund by excluding companies that mined more than 20 million tonnes of coal a year or generated more than 10 gigawatts of power from coal. At the end of 2019, the fund held stocks worth $1.6 billion in such companies, according to fund data. Wednesday’s announcement, in a statement issued by the fund, is the first to show the tougher rules being applied.
A broadening set of ESG-related oversight responsibilities, evolving case law, and increased investor scrutiny prompt companies to seek innovation in director compensation design.
At its core, the director role is primarily one of stewardship rather than execution. While “pay for performance” has become a mantra for executive compensation in the last decade, the concept does not extend in the same way to director pay. Rather, director pay structures are oriented toward compensating for time commitments and leadership. Retainers and per- meeting fees for board and board committee services reflect the time spent on company- related activities. Supplemental retainers for board chairs, lead directors, and board committee chairs reward the additional responsibility of service in leadership positions. To be sure, equity grants are widely used but, rather than being linked to specific performance measures, they are meant more generally to establish an ongoing interest in the long-term prospects of the business.
(Bloomberg Opinion) -- Japan is casting an even wider protectionist net to shield its big companies. It has less to do with defending against unsolicited overtures into strategic assets than with squeezing out troublesome foreign investors. The moves will strangle what’s left of the drive to reform corporate governance and undermine long-suffering households as an economic crisis takes hold. Last Friday, Tokyo laid out details of new rules that restrict overseas investment through amendments to its Foreign Exchange and Foreign Trade Act, in a bid to preserve industries in the interest of national security. A so-called core list includes giants like Toyota Motor Corp. and Softbank Group Corp. that amounts to 40% of the benchmark Topix by market capitalization. The government also spelled out much-awaited exemptions that establish whether outside investors are subject to the rules. The effect is to add onerous hurdles to what had been an open market, nearly one-third owned by foreigners who account for most of the daily turnover, according to Goldman Sachs Group Inc.
Every industry across the globe has faced a crisis at some point in time. While most large companies survive, many struggle for years following a period of severe adversity. Others prevail and become stronger than before.[...] The pandemic’s impact will be felt differently by every company, and boards will have to ramp up or dial back their responses depending on their unique circumstances. [...] As the outbreak took hold, we spoke with almost twenty seasoned directors and active and retired CEOs to glean their lessons for boards on navigating the uncertainty and adapting to new challenges. This is what they recommend.
Many REIT boards are now broadening their focus beyond the immediate firestorms unleashed by COVID-19, to longer-term risk-management and strategic planning issues that take account of the radically changed environment. Following is a list of 15 key issues to be considered with a 3-, 6- and 12-month lens, and beyond. Many boards have already considered these issues in crisis-mode, but it is essential to also reflect on them more broadly as we move into the next phase of response and as expectations for the recovery adjust to take account of the realities on the ground. Of course, the analysis around each of these issues will differ by sector, sub-sector and company, and there are unfortunately no one-size-fits-all answers.
Japanese industry once led the world in research, product development, and innovation. It could do so again. Japan’s industrial R&D departments are no longer achieving world-beating performance. At the macro level, the evidence has been clear for some time. The country has slipped in global rankings for productivity growth and intellectual-property generation, even as R&D expenditure remains high. And at the micro level, our research reveals that R&D leaders in Japan have lost confidence in the ability of their organizations to meet the challenges they face.
We are all too familiar with the many ways in which the COVID-19 pandemic has transformed our personal and professional lives over these last several months.[1] We are confronting new and serious personal challenges, all the while endeavoring to continue our respective professional responsibilities. Like most of you, the SEC Staff have been teleworking since March. The disruption and changed work environment has had – and will continue to have – a substantial impact on the activities of the Division of Enforcement. But I am gratified to report that we have continued to execute on our important mission to protect investors, promote capital formation, and maintain fair and orderly markets.
Commercial aviation is seeing its darkest period ever. That’s according to Air Canada chief executive officer Calin Rovinescu. Mr. Rovinescu, who has led the airline since 2009, is grappling with a simple yet thorny question. How do you balance the books when no one wants what you’re selling? [...] So far, demands have included the usual hot-ticket items – things such as capping executive pay, axing hefty bonuses and eliminating stock buybacks. None of these are necessarily bad ideas. For example, using public funds to buy back company stock, a move that largely benefits corporate executives, defies logic. Eliminating this practice would be a good start. But what Canadians would really benefit from – what Air Canada should promise in exchange for using our cash – is an end to practices that aren’t in the public interest. [...] On paper, air-service agreements benefit consumers by offering more choice. In practice, however, these agreements are often used by incumbent carriers to preserve market share at the expense of consumers. And Air Canada is arguably one of the worst offenders.
Voting on shareholder proposals is a poor way to drive change at portfolio companies, according to T. Rowe Price. The $1 trillion asset manager said in a report Monday that investors are increasingly interested in shareholder proposals, but these votes matter less than some may think. “Shareholder proposals are non-binding votes that are nearly always opposed by the company’s management and typically find little support.” Nevertheless, “We see keen interest in our approach to voting on such resolutions, given mounting investor concern in this area,” the report said. Engaging one-on-one with a portfolio company is far more valuable — and effective — when it comes to pushing for change, in T. Rowe Price’s experience.
|