Your new post is loading...

|
Scooped by
Institut sur la gouvernance (IGOPP)
August 2, 2021 10:05 AM
|
Hedge funds are looking to buy into unlisted companies, betting that an area of the markets that has wrongfooted the industry in the past can now provide them with the kind of lucrative gains enjoyed by private equity rivals. High-profile executives such as Third Point’s Daniel Loeb, Marshall Wace’s Paul Marshall and BlueCrest Capital’s Mike Platt are among those who have spotted the opportunity. They are now seeking to invest directly in fast-growing companies, particularly in the technology sector, that are staying private for longer and can already be richly valued before they float. [...] Many hedge fund managers, who have traditionally invested in public markets, have also been looking with envy at the returns, fees and investor inflows enjoyed by the private equity and debt industries in recent years. Assets in private capital have risen from just over $2tn in 2010 to more than $7tn at the end of last year, according to Morgan Stanley. The hedge fund industry has grown from $1.9tn to $3.6tn over that period, according to HFR, and performance has often been lacklustre. This is not the first time hedge funds have expanded into private equity and unlisted companies. Before the 2008 financial crisis some managers bought into private companies to juice up returns. That move backfired spectacularly when the crisis hit and many such assets became tough to sell, just as investors were demanding their money back.
The responsibilities of boards of directors continue to evolve and increase, particularly given the events of the past year. In addition to perennial topics such as strategy, succession, financial reporting, compliance, and culture, boards are experiencing broader demands on their oversight from expanding stakeholder and shareholder considerations; continuing challenges of the ongoing global pandemic and its aftermath; and addressing the changing role of the corporation in society at large on matters such as racial justice and climate. The growth in the number and complexity of board responsibilities is taking place in an environment of growing skepticism towards our various institutions. Against that background, companies and their boards can help to address these multiple challenges by considering one of the most critical assets not on their balance sheets―trust.
ExxonMobil does not plan “huge shifts in strategy” after losing a hard-fought shareholder vote to a hedge fund that had pushed the oil supermajor to better prepare for a future of cleaner fuels, its chief executive said as he reported financial results bolstered by higher crude and chemicals prices. [...] At Exxon, the tiny hedge fund Engine No 1 won three seats on the board after a campaign that claimed that its focus on fossil fuels put it at “existential risk”. Woods told analysts “the time is right” to step up the company’s low-carbon efforts given the “growing recognition of the importance of carbon capture and storage, hydrogen and biofuels by both governments and investors”. But he said that the shareholder vote defeat was not likely to herald “huge shifts in strategy”. The company could make “additional emphasis” in areas where it has already been focused, such as carbon capture and hydrogen. Woods noted potential new carbon capture projects, including in Wyoming and the port of Rotterdam, but warned that it would take time to “get steel in the ground”.
[...] À elle seule, cette partie qui concerne les activités saoudiennes représente le quart des produits tirés des activités d’hydrocarbures du secteur des Ressources de SNC-Lavalin. «La clôture de la vente d’une part importante de nos activités de pétrole et gaz du secteur Ressources marque une autre étape importante d’un parcours qui a commencé il y a deux ans, au moment où nous avons annoncé pour la première fois notre initiative stratégique visant à simplifier nos activités et à réduire davantage les risques pour notre entreprise», a indiqué Ian Edwards, président et chef de la direction du Groupe SNC-Lavalin inc. Le géant québécois de l’ingénierie veut ainsi se concentrer sur ses services professionnels d’ingénierie et la gestion de projet. «Nous avons réorienté nos activités pour nous concentrer sur la croissance de notre offre de services d’ingénierie de base qui présentent un potentiel élevé, notamment nos secteurs de l’Ingénierie, conception et gestion de projet, de l’Énergie nucléaire et des Services d’infrastructure», a ajouté M. Edwards.
But ESG makes headlines during proxy season, according to data from Insightia. The number of companies targeted by an activist during the first half of the year was at its lowest level in more than six years, according to Insightia’s half-year shareholder activism review. Between January 1 and June 30 this year, 518 companies were targeted by activist investors. This is a notable decrease compared to the first half of 2020, when 594 companies were targeted, and is a long way short of the all-time high of 2018, when 710 companies were in the crosshairs. More than half of these campaigns (302) were launched in the United States, with Japan (43) and Germany (31) rounding out the top three countries with the most targeted companies. Shareholder activists have shown more comfort with launching campaigns at large cap companies in recent years, and that continued during the first half of 2021.
- Regulators and investors are focused on ESG-related disclosure requirements, particularly on climate
change and board and workforce diversity. Requirements are likely to be extended to US public
companies and US investment funds, as well as private companies and subsidiaries operating in the
EU and UK. - The risk of ESG-related litigation, regulatory action and shareholder proxy battles continues to grow.
Companies should comprehensively review their ESG-related strategy and disclosure, including in
materials not filed with authorities or used in securities offerings. - The global sustainable finance market is likely to be significantly boosted by new central bank and
regulatory actions, but more rigorous criteria for ESG-labeled products are also being implemented.
Companies should consider relevant opportunities to participate in this market. - Financial regulators are focusing on climate risk management and climate change’s effects on
financial stability. Financial institutions should assess their current approach to climate risks and
opportunities and prepare for related new requirements and supervisory expectations.
- According to the Economic Policy Institute, the CEO-to-employee pay ratio increased by 1000% in the past 40 years.
- US public firms were mandated to report on this gap by the 2010 Dodd-Frank Act, with the first gap data becoming available in 2017.
- A recent report examines the effect of CEO gender and minority status on the size of the compensation gap between a firm’s CEO and its average worker.
Kamala Harris’ election as US Vice-President has drawn attention to the fact that female and minority leaders are underrepresented in all walks of life. This is especially evident in the corner office of US companies. Despite their unique leadership qualities, data from 2017-2018 for S&P 1500 firms shows that women hold only 5%, and minority representatives only 7% of CEO positions. Recently, the TIAA named Thasunda Brown Duckett as its CEO, only the second-ever Black female chief executive in the Fortune 500.
The U.S. and its allies have long pressed China to stop helping favored industries with subsidies, government preferences and other interventions. Now they are beginning to copy it. Last month, the U.S. Senate voted for direct industry subsidies with little precedent: $52 billion for new semiconductor fabrication plants, called “fabs.” Other regions have done the same. The European Union has committed to nearly doubling its share of global semiconductor manufacturing capacity, to 20%. South Korea approved up to $65 billion in support for semiconductors, and Japan promised to match other countries’ semiconductor aid while planning to turn Japan into an Asian data center hub. [...] Collectively, this represents an embrace of “industrial policy,” the idea that governments should direct resources to industries critical to the national interest rather than leaving things to the market.
Despite being one of the more well-known doctrines in corporate law, the rule articulated in Blasius [1]—that directors who act with the primary purpose of interfering with a stockholder vote must have a compelling justification for their conduct—has received little attention from the Delaware Supreme Court. Delaware’s highest court has not mentioned the Blasius test in over a decade [2] and has not held that a board’s conduct triggered the Blasius test since 2003. [3] During those intervening years, Blasius has been questioned, diluted, and declared all but subsumed by other doctrines. As one vice chancellor put it, a consensus has taken root that “Blasius ‘ main role, to the extent it has one, is as a specific iteration of the intermediate standard of review laid out in Unocal.”
[...] For the moment, social enterprises – like other “social economy” organizations – have been harnessed to act as surrogates for governments in coordinating the administration, financing, and implementation of domestic social and welfare policy.[1] To a greater or lesser extent, therefore, social enterprises are regulated domestically by individual member states of the EU (“Member States”), “with little private leeway for initiative-taking outside government policy”.[2] This means that social enterprises do not enjoy the freedom of establishment, in the way that traditional corporations do, as provided for by the EU treaty framework and the CJEU’s case law.[3] Consequently, there is no European social enterprise law market; social enterprises lack cross-border mobility and are confined to the particular jurisdiction of incorporation.
The COVID-19 pandemic has been the catalyst of unprecedented changes to the business landscape. Issues that were trending even before the pandemic have been accelerated to the top of board agendas, including workforce policy, talent recruitment and retention, digital transformation, cybersecurity, brand and reputational risk, ESG and DEI, to name a few. These trends are being reflected in changes to board member recruitment practices, as boards felt pressure to augment their existing talent pool with new directors with different skill sets and experiences. [...] The message coming from directors was clear: they see “cognitive diversity” (different ways of thinking) in the boardroom as a strategy to successfully navigate crisis and change. Diligent Institute set out to measure whether these sentiments are translating into new director recruitment and appointments. In other words, are boards actually appointing directors from nontraditional professional backgrounds?
Canada has submitted a bid to host the headquarters of the new International Sustainability Standards Board (ISSB), a proposed group that would develop rules for how companies report on environmental, social and governance matters. The ISSB is a creation of the U.K.-based IFRS Foundation, which manages the International Financial Reporting Standards used by Canadian companies that trade on public stock exchanges. The ISSB will create a global set of sustainability standards rather than continue with companies picking from among multiple existing frameworks for disclosing these issues. Chartered Professional Accountants of Canada, an industry body, has been calling for international standards. [...] The bidding group hasn’t identified where the office would be located if Canada is successful but six cities – Calgary, Mississauga, Montreal, Ottawa, Toronto and Vancouver – have signed on as “supporters” of the effort. The Logic, an online publication, first reported the effort and said economic development groups in Montreal and Toronto are preparing bids.
President Joe Biden’s tougher Buy American rules, potential protectionism in his US$550-billion infrastructure package and a vow to move medical and military supply chains out of foreign countries are raising fears that Canadian companies will be squeezed out of the U.S. government procurement market. Mr. Biden on Wednesday unveiled his long-promised tightening of the Buy American Act. Under his new rules, goods bought by the U.S. federal government – from vehicles to construction materials – will have to contain 75 per cent U.S.-made content by 2029, up from 55 per cent today. Contractors will also have to provide more paperwork to the government to prove that they are complying with these content requirements. “They’ve got a new sheriff in town,” the President said at a Mack Truck assembly plant in Macungie, Pa. “We want to be the ones making the innovative parts of every product.”
|
|
|
Scooped by
Institut sur la gouvernance (IGOPP)
August 2, 2021 10:03 AM
|
Donald Trump entered July with a war chest of more than $100m from his 2021 political committees, raising more than other Republicans in online donations during the first half of this year, new federal campaign finance filings show. Trump’s enormous cash flow — unprecedented for a former president — has renewed speculation that he is considering a 2024 campaign. But not all of the money can be used towards re-election efforts. The sum is testament to his enduring popularity among Republicans, even after he lost the 2020 election and was stripped of his preferred communication platform when Twitter banned his account in January. The majority of the cash on hand — $90m — came from the Save America political action committee (Pac). The rest has accumulated across several other fundraising vehicles, some left over from his 2020 presidential campaign, others newly launched, making it difficult to keep track of the money Trump has raised and what he is able to use it for.
Amazon.com Inc. has been fined 746 million euros, equivalent to $887 million, by a European Union privacy regulator for violations related to its advertising, by far the largest-ever fine under the EU’s data-protection law. The fine, which Amazon disclosed Friday in a securities filing, was issued two weeks ago by Luxembourg’s privacy regulator, the CNPD, and accompanied by an order to revise certain business practices that Amazon didn’t specify. Amazon said the regulator’s decision was without merit and that it would appeal in court. [...] The record fine is a sign that EU privacy regulators are taking a more aggressive stance on enforcement, some three years after the EU’s privacy law, the General Data Protection Regulation, went into effect. So far, the largest fine under the GDPR was a €50 million fine against Google in 2019.
Voluntary industry-wide agreements have recently emerged as a way to promote corporate social responsibility (CSR). Competitors in industries as diverse as chocolate production, fashion design, and truck manufacturing aspire together to pay fair wages or transition to less polluting products. A growing management literature endorses the idea. Henderson (2020), for instance, calls for “industry-wide cooperation” to stop environmental degradation and economic inequality.
In mid-June, US president Joe Biden held talks with his Russian counterpart Vladimir Putin to discuss a recent scourge of cyber attacks against the US, including by Russian-based criminal ransomware hackers. Biden has said he told Putin in no uncertain terms that “certain critical infrastructure should be off limits to cyber attack — period”. Nevertheless, data show that ransomware attacks continue apace, including in sectors such as healthcare and education. It is unclear whether Biden will take further action in light of this. Ransomware, which usually involves hackers seizing an organisation’s data or computer systems and only releasing access if a ransom is paid, has long plagued businesses large and small. The first known ransomware virus, PC Cyborg, was recorded in 1989, with victims infected via floppy disk and told to send a $189 cheque to an address in Panama. Today, these financially motivated hacks are far more sophisticated — and are proliferating fast. Attacks have quadrupled during the pandemic, SonicWall data show, partly because the shift to remote working has left staff more vulnerable than if they were connecting to more secure corporate networks.
As any banker knows, capital is crucial. Sufficient capital is needed for a bank’s growth; to withstand losses on loans, lack of earnings, and downturns in the economy; and, of course, to keep the regulators happy. There are many ways a bank can raise capital, including selling stock and issuing debt. If the bank is part of a holding company, which most banks are, it is the holding company that raises the capital and downstreams it to its subsidiary bank. The holding company, thus, might sell its stock, issue debt such as subordinated debt, or borrow funds through a standard holding company loan. Typically when a holding company sells its stock, it does so through exemptions from registration under state and federal securities laws. But sometimes the management considers a public sale of its stock — i.e., going public. This article focuses briefly on the advantages and disadvantages of going public.
After slowing for some of 2020 during the pandemic, activist investors are back. Many boards will benefit from asking themselves some of the questions activists would ask—before activists do. As boards adjust to new norms following the events of the last year, thoughtful boards will understand that the new demands on them and the agility many discovered during the pandemic together present an opportunity to reassess themselves and senior leadership teams and make changes that might not have been possible before. Furthermore, if boards don’t undertake a reassessment themselves, activists may well see new opportunity. Following the pandemic-related downturn in activist activity of mid-2020, the first quarter of 2021 saw a second consecutive quarter of elevated global activity—53 new campaigns were initiated, which is in line with first-quarter 2020 levels.
The shockwaves that have wiped billions of dollars off Chinese shares in recent days are part of a regulatory assault that is expected to extend beyond tech to all private-sector areas of business in the country. What initially started in November with the suspension of the $37bn initial public offering of billionaire Jack Ma’s fintech, Ant Group, has broadened this month into an investigation into data security at ride-hailing app Didi Chuxing and devastating restrictions on the tutoring industry. Experts and companies warn that the turbulence shows no signs of easing as the Chinese government rolls out a sweeping new legal framework for how businesses collect and use data.
#1. What are the new laws?
#2. What are the key grey areas?
#3. Who will the regulators target next?
Over the last decade, investors have shown a growing appetite for socially responsible investing (SRI). SRI funds, who advertise that they care about environmental and social issues in addition to maximizing returns, have more than doubled their assets under management. This trend is consistent with the proposals of some academics (e.g. Bérnabou and Tirole (2010) and Hart and Zingales (2017)) that corporations should seek to maximize shareholder welfare and that SRI funds should play a role in addressing environmental and social issues. Whether this approach can increase social welfare is an issue of heated debate in the literature (see, for example, Bebchuk and Tallarita, 2021).
Public companies could be required to disclose climate-change related risks to investors in regulatory filings under a proposal being formulated by the Securities and Exchange Commission, a step that could expose them to new litigation threats. SEC Chairman Gary Gensler said Wednesday he has asked agency staff to consider whether climate-related disclosures should be filed in companies’ annual reports, known as Form 10-K, along with financial data and other information considered crucial to investors. That would require them to provide statements that are both complete and accurate, making it easier for SEC enforcement attorneys to investigate firms or their directors for fraud or disclosure failures. [...] For companies, climate change can involve both physical risk, such as extreme weather events that can cause unexpected losses, as well as transition risk, which includes government policies that force a move away from fossil fuels. California, for example, has indicated it will ban sales of new gasoline-powered vehicles in the next decade. Current SEC guidelines suggest both types of risks might need to be disclosed in federal filings. But the guidance doesn’t spell out specific, required disclosures, and companies decide what to say about risks.
Robots constructing homes may sound like science fiction. Yet a Toronto-based startup aims to make this futuristic idea a reality within the next year, leveraging advances in automation, advanced manufacturing, cloud computing and artificial intelligence (AI). Promise Robotics was launched in 2019 by founders Ramtin Attar – a former technology lead at a multinational technology company – and Reza Nasseri, the chief executive officer of Landmark Homes. [...] Already, the company has an early-stage factory that should be able to build components later this year. When fully developed, Mr. Attar says the advanced manufacturing platform will be able to build homes significantly faster, leading to as much as a 40-per-cent cost savings over current methods. For a single-family home, for example, “traditional framing would take three to four people three or four weeks, depending on complexity,” he says. “We are aiming to do the same in about a day or two.”
We often hear about a board of directors being sued, but can a plaintiff really sue a corporation's board? According to a recent decision by the Federal Circuit, a plaintiff can't sue a board, at least not as a separate entity in federal court: [...] We are persuaded that, under California law, a plaintiff may not sue a corporation's board of directors as an entity separate from the corporation. Siegler v. Sorrento Therapeutics, Inc., U.S. Ct. of Appeals Case No. 2020-1435 (Fed. Cir. July 20, 2021). The plaintiff argued, albeit unsuccessfully, that Section 14 of the Clayton Act provided the requisite authority. The Federal Circuit pointed out that the statute imposed liability on individual directors and was criminal, not civil.
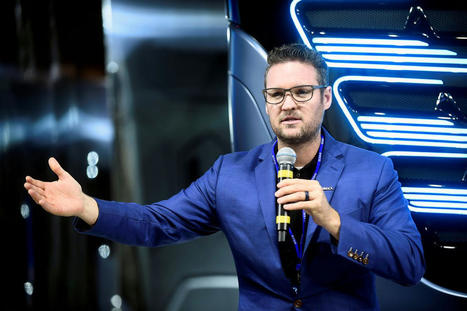
Trevor Milton, the founder and former chief executive of Nikola Corp, was criminally charged on Thursday with defrauding investors by lying to them about the electric– and hydrogen-powered truck maker. In an indictment, prosecutors in New York charged Milton with two counts of securities fraud and one count of wire fraud over his statements from November 2019 to September 2020 about Nikola’s products and technology. Prosecutors said Milton, 39, misled investors in order to drive up Nikola’s stock price, become one of the world’s 100 richest people, and “elevate” his stature as an entrepreneur. “Milton lied about nearly every aspect of his business,” U.S. Attorney Audrey Strauss in Manhattan said at a news conference.
|