


The Securities and Exchange Commission has proposed significantly increasing the threshold for money managers like hedge funds that must file 13F documents, but that would be a wrong move for companies and investors alike.

 Your new post is loading...
 Scoop.it! The Securities and Exchange Commission has proposed significantly increasing the threshold for money managers like hedge funds that must file 13F documents, but that would be a wrong move for companies and investors alike. 
No comment yet.
Sign up to comment
Scoop.it!
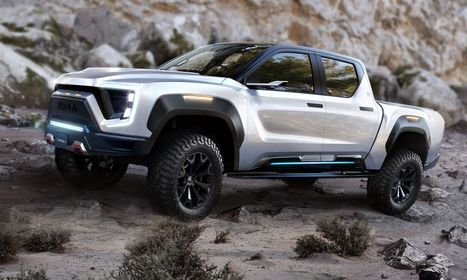
General Motors Co said on Tuesday it was acquiring an 11 per cent stake in U.S. electric truck maker Nikola Corp, worth about $2 billion, and will team up with the company to make a pick-up truck.
Scoop.it!

Managers with different abilities may make various decisions in economic and financial crisis conditions. Real earnings management, as an important issue, is in the centre of attention for many managers in a crisis condition. In this paper, the role of managerial ability in real earnings management is studied in conditions of economic and financial crisis. This study shows that the managers with higher ability take less usage of real earnings management. The results also indicate that managerial ability, economic and financial crisis have significant and negative effects on real earnings management. This negative effect of managerial ability on real earnings management increases in the conditions of economic crisis. Paying attention to the firms' managerial ability, especially in critical conditions, will lead to more accurate decisions by activist investors.
Scoop.it!

The focus of corporate decision-makers on short-term shareholder value maximisation rather than on the long-term interests of the company reduces the long-term economic, environmental and social sustainability of European businesses. The objective of this study is to assess the root causes of “short termism” in corporate governance, discussing their relationship with current market practices and/or regulatory frameworks, and to identify possible EU-level solutions, also with a view to contributing to the attainment of the UN Sustainable Development Goals and the goals of the Paris Agreement on climate change. The study focuses on issues contributing to “short-termism” in company law and corporate governance, which have been grouped around seven key problem drivers, covering aspects such as directors’ duties and their enforcement, board remuneration and composition, sustainability in the business strategy, and stakeholder involvement. The study suggests that a possible future EU action in the area of company law and corporate governance should pursue the general objective of fostering more sustainable corporate governance and contributing to more accountability for companies' sustainable value creation. For this reason, for each driver, alternative options characterised by an increasing level of regulatory intervention have been assessed against the baseline scenario (no policy change).
Scoop.it!
A 5-minute guide to support Remuneration Committees, Heads of Reward and Compensation Professionals when selecting software and tools for remuneration decisions. We live in a digital age where access to information has never been easier. No longer having to scroll through complex and endless spreadsheets and obtain an analytical degree to understand trends - insights and information is at our fingertips. For Remuneration Committees, Heads of Rewards and Benefits, and Compensation Professionals it is no different. Ensuring executive remuneration, bonuses, and incentives are in line with market standards, has never been under such scrutiny. Activist activity has increased in 2020, with traditional investors changing their position from passive to active engagement and focusing on executive pay. In a recent article by the Financial Times, it was reported that misalignment of incentives and negative say-on-pay votes at annual meetings increase the likelihood of a company suffering share price underperformance. Software that provides flexibility for assessing remuneration in comparison to peers, and supports say-on-pay resolutions, is available and increasingly implemented by companies, activist investors, and proxy advisors. When a user begins searching for remuneration software there are questions typically asked:
Scoop.it!

As part of their oversight duties, boards of directors are expected to periodically review their company’s organizational documents. Challenges posed by the COVID-19 pandemic and related economic stresses have exposed various opportunities to improve companies’ organizational documents. In light of the ongoing impacts of the current pandemic and the possibility of similar future shocks, we believe this is an opportune time for boards to take a fresh look at their organizational documents.[1] Specifically, we recommend that boards evaluate potential revisions to their bylaws to allow for greater flexibility and clarity relating to shareholder meetings and board actions. In addition, the board of any company that has recently experienced a significant decrease in its stock price (or any similar vulnerability) should review the company’s takeover defenses and preparedness in the event of shareholder activism or a hostile takeover attempt. For companies that have already held their 2020 annual meeting and do not face a pending threat, any near-term revisions to the company’s takeover defenses would have the benefit of being adopted on a “clear day,” as described further below.
Scoop.it!

On May 27, 2020, the staff of the SEC’s Division of Investment Management withdrew previously issued guidance addressing the intersection between state control share acquisition statutes (control share statutes) and the voting requirements under Section 18(i) of the Investment Company Act of 1940. Under its new no-action position, the SEC staff stated that it would not recommend enforcement action against a closed-end fund for opting into and triggering a control share statute if the boards decision to do so was taken with reasonable care on a basis consistent with other applicable duties and laws. Generally, control share statutes provide that when a shareholder acquires a certain percentage of voting power of a company equal to a “control share,” that shareholder will have no or limited voting rights with respect to those shares. The percentage of voting power equal to a control share is specified in the statue (e.g., one-third but less than a majority). Voting rights can typically be restored to control shares only by a vote of the other shareholders. Control share statutes provide companies with the ability to prevent certain changes of control and protect from shareholder activism. Control share statutes, like other state corporation statutes, require companies to opt-in or opt-out of compliance with the statute’s provisions.
Scoop.it!

Research documents the performance effects of attending to shareholders and treating employees well but underplays national differences in the relative power of labor and capital. We advance a configurational perspective that acknowledges the fit between stakeholder engagement, context, firm attributes and performance. As a cornerstone of this perspective, we develop a typology of stakeholder engagement strategies expressing how firms navigate the tension between conforming with local expectations—by prioritizing shareholders or employees, according to context—and being distinctive—by diverging from their peers. Analyzing a cross‐national sample of firms from 2004 to 2011, we identify combinations of engagement strategies, firm attributes, and contexts linked to high performance. Our findings highlight the multiple context‐dependent paths, which link stakeholder engagement to high firm performance.
Scoop.it!

Shareholder disputes arise in both good and bad economic times. While such disputes have risen steadily since the 2008 financial crisis, the emergence of coronavirus (COVID-19) is expected to lead to a significant uptick in disagreements within the ranks of the many companies struggling to rebuild in the face of a global economic downturn. Amid COVID-19 and in a post-pandemic environment, the growth and evolution of shareholder disputes will remain a key feature of the corporate landscape in the years ahead. FW: To what extent are you seeing an increase in the number of shareholder disputes in today’s business world ? Williams: We have seen a steady rise in shareholder disputes since the onset of the 2008 financial crisis and are already seeing signs of a further uptick in the trend brought on by coronavirus (COVID-19). This is highly likely to continue in the post-pandemic world. These involve both public and privately held companies across a wide variety of industries, including in the financial sector, as well as in the oil, gas and construction sectors. Bédard: Shareholder disputes and corporate disagreements constitute a steady stream of international disputes – they are perhaps the most frequent type of disputes handled by arbitration counsel at large corporate firms. Shareholder disputes arise both in good and bad economic times. But challenging financial situations probably bring additional sources of tension inside corporate organisations. Typical drivers of shareholder disputes are a lacklustre economy, disappointing financial results and major corporate reorganisation. The global COVID-19 pandemic may generate a surge in shareholder disputes, as a difficult business climate intersects with individual corporate struggles to manage unprecedented circumstances.
Scoop.it!

Shareholder activism has been on the rise in Japan. Will the trend continue in the post–COVID-19 world? Shareholder activism in Japan rewards shareholders with positive abnormal returns, at least in the short run. That’s according to a new study we conducted at the Monash Centre for Financial Studies. This finding suggests that by actively engaging with investee companies, investors could potentially unlock shareholder value. However, recent protectionist moves by the Japanese government may hinder such efforts, especially for foreign investors. Shareholder activism is broadly defined as the application of pressure by shareholders to influence or change company behavior. It comes in various forms and can involve public campaigns as well as private engagement between shareholders and companies. Unlike in the United States and Europe, where investors are increasingly focused on environmental, social, and governance (ESG) issues, in Japan thus far business performance and governance have been shareholder activism’s dominant focus. Until about a decade ago, public shareholder activism in Japan was rare, and nearly always unsuccessful, particularly when it involved hostile campaigns by foreign investors. The most famous of these came in 1989 when US investor T. Boone Pickens made a bid for three board seats at Koito Manufacturing Co. Toyota, a key Koito shareholder and customer, along with other shareholders, voted it down. It was one of several high-profile early examples of cross-shareholdings — a common feature of corporate culture in Japan — and the use of business ties to suppress activist shareholders.
Scoop.it!

SYDNEY (Reuters) - Shareholder activists in Japan are taming calls for their targets to return their cash piles to investors, ceding ground to the view such corporate hoards are assets rather than a drain on returns amid the economic pain of the coronavirus pandemic. The change in stance comes as Japan - the second-biggest market for activists after the United States - enters peak season for company annual general meetings (AGMs), where proposals for measures such as dividend increases and share buybacks would normally be presented. Fifty-four companies have so far received shareholder proposals for this year’s AGMs in June as of Tuesday, matching the record set last year, according to data compiled by Mitsubishi UFJ Trust. “The vast majority of activist demands made last year were related to right-sizing balance sheets. But asking for buybacks amid corona-chaos seems a stretch,” said Nicholas Smith, Japan strategist at CLSA. [...] Japanese institutional investors, who have increasingly joined activists in pressuring boards to improve returns, have also eased up in their demands. [...] “Companies are likely to be in need of a comfort blanket, worrying about the ‘second wave.’ That cash is probably not going anywhere,” Smith said. “So the presents are still under the Christmas tree. We’re just going to have to wait a little longer to open them.”
Scoop.it!

What happens to companies in the years after they are targeted by an activist hedge fund? Often, there is a shift towards short-term value creation at the expense of long-term competitiveness and sustainability, and a transfer of wealth from stakeholders to short-term shareholders, according to new research published in the Strategic Management Journal. [...] At a time when activist hedge funds are gaining power and influence, providing comprehensive evidence on the long-term financial and non-financial implications of their activities is critical. For policymakers, our results suggest that restraining activist hedge funds can help build more competitive and sustainable companies over the long term. It would be prudent to enforce regulations that require activist hedge funds to hold onto their shares for longer periods of time and penalise them when they sell out early and leave a company worse off. For corporate executives, it is necessary to anticipate defense strategies for when activist hedge funds come knocking. In almost all cases, activist hedge funds depend on the support of other shareholders to back their proposed interventions. The better executives are at communicating their companies’ long-term value creation story to existing shareholders, the more success they will have defending against short-term interventions. For investors who care about sustainability, it is worth carefully dissecting one’s investment portfolio. Today, many individuals and organisations are unknowingly invested in activist hedge funds through their pension funds and endowments. Socially-minded investors should ensure their capital is not supporting investment strategies that risk undermining their personal social priorities.
Scoop.it!

A couple of crosscurrents are occurring within the oil industry. While many corporate boards are defeating efforts by activists to disclose more and more climate risks, most are already taking bold action to curtail their CO2 emissions. The broader question is whether large institutional investors and shareholder activists are increasing value by demanding more transparency. One school of thought concludes that as long as they are in tune with their fiduciary roles, they have a right to pursue societal objectives. For companies to profit over the long-term, they must, therefore, act not just in the interest of their stockholders but also for the benefit of the communities where they reside. Others, though, see the current pressures as overkill. Corporations, generally, already provide investors with essential data, critics say. They note that if left to their own devices, the activists would micromanage companies. Their concern is that no matter what measures businesses take to limit their carbon footprints, they will never be enough. If that is the case, then other areas that need oversight will be neglected and shareholders will get hurt.
|
Scoop.it!
The new proxy voting rule changes were justified based on allegations, mostly made by corporate managers, that proxy advisor recommendations are error prone, rife with conflicts of interests and that proxy advisors wield outsized influence over the shareholder voting process.
Scoop.it!

High-performance boards are adapting to the reality that we are working in a virus-charged world, adjusting their governance protocols accordingly. Thinking unthinkable scenarios is no longer a fantasy exercise, it is pragmatic risk management. The challenge is to emerge from these paradigm shifts stronger than before, with the ability to sustain and increase value for all stakeholders.
Scoop.it!
In this paper, we investigate how auditors respond to shareholder activism against their clients. Our study is important because activism may be viewed by auditors as a source of increased engagement risk, thereby impacting audit outcomes. The potential relationship between shareholder activism and audit outcomes leads us to predict that activism targets will pay higher audit fees and also will be more likely to receive adverse internal control opinions and first‐time going concern opinions. Our results, which support all three predictions, suggest that the public scrutiny associated with activism campaigns heightens auditors’ concerns about reputational damage and litigation risk. Consistent with this notion, we find that activism targets are more likely to experience accounting‐related lawsuits. We also find that the increased likelihood of adverse internal control opinions documented in our baseline tests reflects higher quality reporting rather than increased auditor conservatism. Overall, our findings suggest that activism campaigns spur auditor diligence while also increasing the possibility of negative outcomes that may not be fully anticipated by activist investors.
Scoop.it!

Research shows CEO turnover is higher in US firms than those in Europe and the UK, with 28% of US bosses departing after less than 36 months at the helm. When Expedia’s chief executive Mark Okerstrom stepped aside over strategic disagreements in December, it came after just two years in charge. By leaving after such a brief spell at the top he joined a significant leadership trend: the US beats both the UK and Europe in speed of CEO turnover. According to new research, US companies are more likely to change their lead executives in under three years than companies in Europe and the UK. The research, from shareholder advisory firm SquareWell Partners, reveals that 28% of US corporate leaders parted company with their employers in three years or less. European companies are more likely to offer patience to their lead executives: 29% of their departing leaders are in post for nine years or more, while only 8% exit after less than 36 months at the helm. The largest proportion of departing UK leaders served between six and nine years. Average tenure across all territories for a lead executive is a little shy of seven years. In its report, looking at data for the 18 months to June this year, SquareWell describes the figures as “demonstrating the willingness of US boards to act more quickly in replacing a lead executive”.
Scoop.it!
From
www

When RWC’s Japan Active Engagement team started work more than 15 years ago, “activism” was associated with high-profile attempts by mainly foreign investors to force change at Japanese companies through ownership. “Engagement” was an unfamiliar concept — so much so that there was no Japanese word, and one had to be imported from English: “engage-ment-o”. Interactions between investors and managers were then essentially interrogative. Investors asked the questions and managers, more or less, gave the answers. The notion that investors might make suggestions for changes in the ways in which companies were managed was, at best, novel and, at worst, anathema to Japanese company managers. Many hitherto successful activist investors in other regions who had high hopes of Japan were met with resistance, resentment or policies designed to block their efforts. This led to Japan’s reputation for “value traps”, where poor corporate governance held back investor returns. [...] Pre-Abenomics, 96 per cent of companies held their shareholder meetings on the same day — that number is now 30 per cent. Recent reports suggest that overt shareholder activism is now almost as common in Japan as it is in the US and confrontational events which would have been inconceivable 20 years ago now occur quite often, some with positive results. The lure for these activists is not limited to corporate Japan’s infamous cash pile, or the potential returns from disaggregating keiretsu (group of companies with interlocking business relationships and shareholdings) behemoths from their conglomerate discounts. The appeal also lies in the change in corporate attitudes that, in a country that values consensus, has now reached critical mass.
Scoop.it!

The pandemic has forced many struggling companies to focus on increasing their bottom line. At the same time, recent protests have strengthened the calls for greater diversity at work. And now, according to three studies, there’s evidence that investors don’t think that organizations can do both at the same time. According to three new studies, there’s a belief that a focus on diversity detracts from efforts to maximize shareholder value (it doesn’t). [...] Study #1: Adding Women To Board Decreases Market Value The first study found that as firms increase the number of female directors on their boards, their market value decreases. [...] Study #2: Female Board Members Get Fewer Shareholder Votes When Company Is Struggling In a second study, forthcoming in Organization Science, researchers examined 50,202 board director elections from 2003 to 2015 and found that female board members typically get more support from shareholders than their male counterparts. [...] Study #3: Corporate Social Responsibility Is Perceived As Signal Of Waste By Activist Hedge Funds Activist hedge funds seek out companies that they believe are not maximizing shareholder value, and then they make a large enough investment in that company so that they can influence the company’s management and decision making.
Scoop.it!
Investment banks turn to technology as Covid-19 is set to spur a wave of activist campaigns. UBS has launched a new big data tool to help clients fend off the threat of activist investors, as investment banks brace for a rush of such campaigns in the wake of the coronavirus crisis. The Swiss bank, which has been building a team of investment bankers to help companies defend against activist campaigns in Europe, has launched a new digital system to help companies predict the risk of being targeted by activists — a major driver of mergers and acquisitions activity in recent years. While activist investors, which take large stakes in companies in a bid to agitate for change at the top of the organisation, largely stepped back in the early days of the Covid-19 pandemic so as to give executives breathing space, they have since returned. In May, $3.3bn of activist capital was deployed, according to data from independent investment bank Lazard, which was a 159% increase on March. Darren Novak, head of activist defence at UBS, said that Covid-19 was likely to exacerbate the problems of companies and provide an opportunity for activist investors in the second half of this year. “We anticipate seeing more M&A-related activist campaigns that will likely focus on seeking future opportunities for a quick sale or divestiture when M&A markets reopen,” he said. [...] UBS’s new system — called GUARD (Global Utility for Activism Risk and Defence) — aims to quantify the risk of a company being targeted by an activist by looking at 220 million data points and analyses more than 5,000 historical activism campaigns. UBS follows a number of its competitors by launching sophisticated technology tools that can help both streamline the deal-making process and help clients assess the risk of an activist threat.
Scoop.it!

From
www
Companies have been using online technologies to conduct their AGMs with varying degrees of success. The pandemic has caused the postponement of thousands of AGMs or forced them to be adapted for online. Existing proxy voting technology has proven valuable in this period as a physical presence is not possible
Scoop.it!

The prevailing wisdom is that activist investors can drive corporate short-term behavior singlehandedly. The prevailing wisdom is wrong. At just 0.3% of total global equity assets under management (AUM) in 2018, activists depend on the support of long-term investors for their influence. Without clarity on long-term shareholders’ views, companies perceive short-term pressure coming from their investors and assume the activists speak for the entirety of the shareholder register. Having a strong investor/corporate dialogue well before an activist campaign arises is the way to encourage companies to proactively improve the drivers of long-term value creation—such as bolstering their governance, honing strategies for growth, and engaging with long-term investors. Strong long-term performance is the best way to limit opportunity for an activist campaign. Indeed, rather than being a spectator, long-term investors have a significant role to play alongside companies to counteract short-term activist behaviors. It is well within the power of these long-term investors to either amplify or dampen the short-term impact of activism, serving as essential players of the activism ‘game.’
Scoop.it!
The COVID-19 pandemic had a swift and volatile impact on business operations and the financial markets. The crisis arising from COVID-19 and the efforts taken to prevent its spread occurred simultaneously with the annual incentive award cycle of many companies, forcing companies to address incentive setting and employee retention in a rapidly changing environment. [...] Some boards and compensation committees— particularly those that have weathered significant prior business disruptions—may choose to stay the course and not delay grants. Proceeding with the typical annual grant timing could, when judged in hindsight, create the impression that management received an unjustified windfall, because equity grants were made when the company's share price was artificially (and temporarily) low. Shifting the grant timing could alleviate some of that pressure, but it could also exacerbate it given current uncertainties. An alternative to consider is staggering the annual equity grant to be made over the year (i.e., semiannually or quarterly) to reduce the effects of continuing market volatility and supply chain disruption. [...] Boards and management teams should consult with their legal, tax and accounting advisors before making any decisions regarding changes to their approach to equity and incentive compensation. Further, all actions should be taken with a mindful eye on the potential reactions of all constituents: shareholders, proxy advisors, activist investors and especially employees. To that end, shareholder engagement efforts, in particular during the 2021 proxy season, with respect to say-on-pay voting and whether additional shares will be needed under equity plans, should be considered.
Scoop.it!

The pandemic-related lockdown has affected all market participants, including activist investors. According to data from the Bloomberg Terminal, two relatively new players, Bulldog Investors LLC and Bluebell Capital Partners LP, have joined perennial leader Elliott Management Corp. at the top of the list of activists by the number of campaigns conducted. Bulldog has conducted 15 campaigns as of May 1, followed by Elliott with six. Newcomer Bluebell joins four others with three campaigns during this period. Unlike many activists who target operating companies, Bulldog Investors LLC generally takes positions in under-performing closed-end funds. Closed-end funds are pooled investment vehicles that raise capital through an initial public offering. The fund will list shares on an exchange. Unlike open-end funds, such as mutual funds, which can issue and redeem shares daily based on the fund’s net asset value (NAV), the number of shares in closed-end funds is fixed. Investors will trade shares with other investors, rather than with the fund. Most closed-end funds will make capital gains distributions to investors annually. [...] Bluebell is a long-term investor focused on European public equities. According to the firm, Bluebell “invests in attractive businesses at a significant discount to intrinsic value and seeks to increase shareholder value through constructive engagement.” Bluebell has recently taken positions in Swiss fund manager GAM Holding AG, Cineplex Inc., apparel maker Hugo Boss, and German airline Lufthansa.
Scoop.it!

From
www
Activist shareholders have increasingly focused on ousting top bosses since the coronavirus pandemic took hold of the global economy, according to a new report from investment bank Lazard. In the second quarter, so far, 50% of all campaigns by shareholder activists have involved attacks against boards or management teams, compared to a consistent 33% in the first quarter of 2020 and the whole of 2019. The removal or replacement of top executives at European companies has become a more prominent demand since the onset of the coronavirus pandemic, according to the report. Lazard Head of European Shareholder Advisory, Rich Thomas, told CNBC’s “Squawk Box Europe” on Tuesday that leadership is “never more important” for activist investors than in times of crisis. “That is why we are seeing leadership of companies firmly in the crosshairs of many activists and activist campaigns,” Thomas explained, adding that the coronavirus crisis has taken away some of the traditional tools available to shareholder activists. “The shareholder base does not want to hear about cost reductions, job cuts, they don’t want to hear about return on capital, but when the question is about leadership, and how the board and management is steering the company through this crisis, that can be a little bit more receptive,” Thomas added.
|




